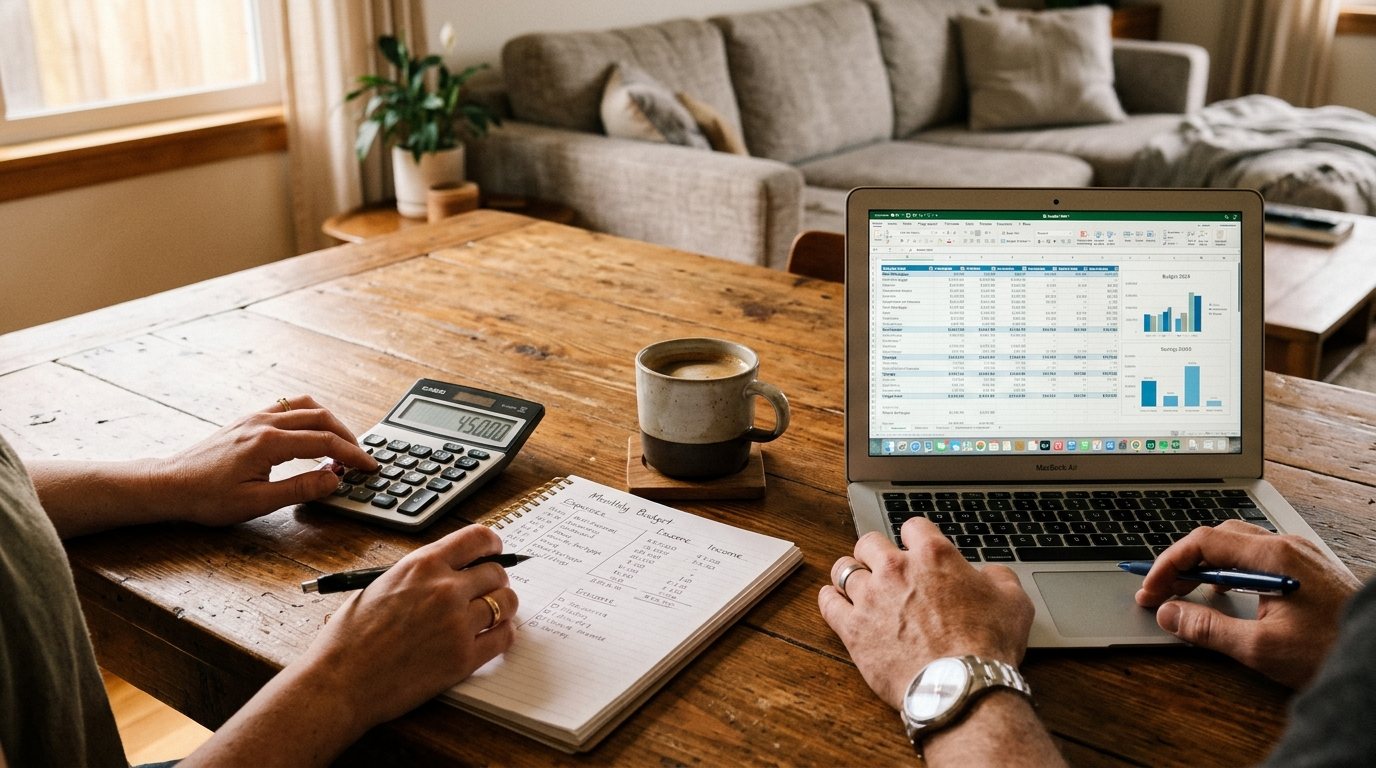
A new sofa, a bed and a dining set add up quickly. Financing lets you take the furniture home now and pay for it over time. It can make a large purchase manageable, but only when you understand the plan you are choosing.
This guide explains the main plan types in plain language, how the two lenders we work with fit in, and the habits that keep a plan working for you. It is general information, not financial advice.
How Furniture Financing Works
When you finance furniture, a lender pays for your purchase and you repay the lender over time. The store is not the lender. The lender decides whether to approve you, and you make your payments to the lender on the schedule in your credit agreement.
At Rockwell Home Furniture, financing is available through Fairstone and Flexiti. The agreement shows the rates, fees and payment schedule before you sign, so you can read the terms before you commit.
The Plan Types, Explained
Most furniture financing falls into three groups. Knowing which one you are looking at is the most useful thing you can do.
- No payments for a period. You pay nothing for a set number of months. If you pay the full balance before the end date, you avoid interest. If you do not, interest is charged, so the end date matters.
- Equal monthly payments. You repay over a fixed term with the same payment each month. Interest applies, and you can usually pay the plan off early.
- Zero interest plans. A promotional plan with no interest for a set term, available when the lender offers it for your purchase.
Pro tip: Put the end date of any no payments plan in your calendar the day you sign, and set a reminder a month earlier. That one habit prevents most surprises.
Fairstone and Flexiti at Rockwell Home
We offer two lenders so you can choose the plan that suits your budget.
- Fairstone is a Canadian lender that has been providing consumer credit for over a century. A 12 month plan with 0% interest is available when it applies to your purchase.
- Flexiti offers no payments for 3, 6 or 12 months, or equal monthly payments over 24, 36 or 48 months. From time to time there are limited time offers, so ask what is available today.
Plans and offers change, so our team shows you the current options and walks you through the terms before you sign.
What to Bring and What to Ask
To start an application in our showroom, bring photo identification and proof of income. Then ask these questions about the plan in front of you:
- When exactly does the no payments or zero interest period end?
- What interest rate applies after that, and on what balance?
- Are there any fees, and when are they charged?
- What happens if a payment is late?
- Can I pay the balance off early, and does it cost anything?
Financing applies to your whole purchase, so decide on the full room before you apply. It is much easier to plan a sofa, a rug and a side table together than to finance them one at a time.
A Simple Way to Compare Two Plans
It is tempting to pick the plan with the longest no payments period, but the end of the plan is where plans differ most. Put two plans side by side and compare these four things:
- The term. How many months before the plan ends?
- What happens at the end. Does the balance have to be cleared, or does it roll into monthly payments with interest?
- The monthly amount. Could you pay it comfortably in your tightest month of the year?
- The total you will repay. Ask for the full amount in dollars, not only the monthly payment.
A plan with a smaller payment is not automatically cheaper. A longer term spreads the cost, but it can also mean more interest overall. Asking for the total repaid makes the comparison fair.
Habits That Keep a Plan Working
- Budget the whole purchase. Add delivery, taxes and any extras, not only the price tag. Our guide to shopping sales wisely shows how to compare real costs.
- Pay a little extra when you can. Extra payments shorten the term and reduce the interest you pay.
- Do not stretch for add ons. If the plan only works when everything goes perfectly, choose a smaller purchase.
- Keep your paperwork. Save your credit agreement and your invoice together.
When Financing May Not Be the Right Choice
Financing is a tool, and it does not suit everyone. If you would struggle to make the monthly payment, or you are unlikely to clear a no payments balance before the end date, a smaller purchase or saving first may serve you better. If you are unsure, ask for the full terms and take them home before you decide.
Financing is subject to credit approval by Fairstone or Flexiti. Rockwell Home Furniture is not the lender and does not make the lending decision. Rates, terms and fees are set by the lender and may change without notice. On plans with no payments for a period, interest is charged if the full balance is not paid by the end date.
Frequently Asked Questions
Which financing options do you offer?
We offer plans through Fairstone and Flexiti. What is available changes, so our team shows you the current options.
Who decides whether I am approved?
The lender does. Fairstone or Flexiti makes the approval decision, not the store.
Can I pay my purchase off early?
On equal monthly payment plans you can pay off early. Ask about the specific plan you choose before you sign.
Will I see the full terms before I sign?
Yes. The credit agreement shows the rates, fees and payment schedule, and our team walks you through the terms before you commit.
See It in Person at Our Calgary Showroom
The easiest way to answer your questions is to talk them through with our team. The Rockwell Home Furniture showroom is at Unit D200, 9737 Macleod Trail SW, Southland Crossing, Calgary. Bring your measurements and your list of questions, or call 825-305-1850. You can also browse our sofas and sectionals online before you visit.
Comments
Loading comments...
Leave a comment
Your email address is never shown or shared. Comments are read by our team before they appear.